


Earn Daily Interest
Access fixed returns from short-term lending

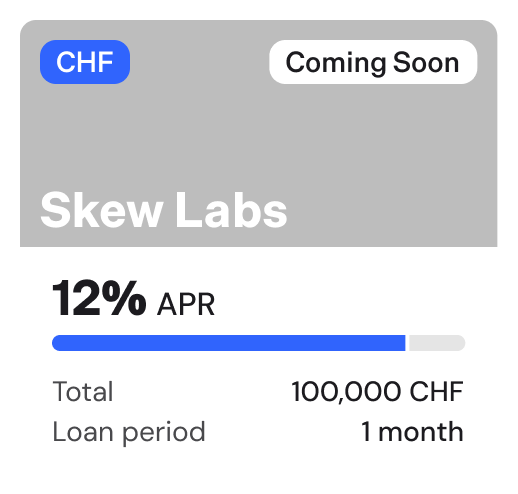

Traditional finance keeps a large share of the difference between what borrowers pay and what lenders earn. On Skew, you earn more.
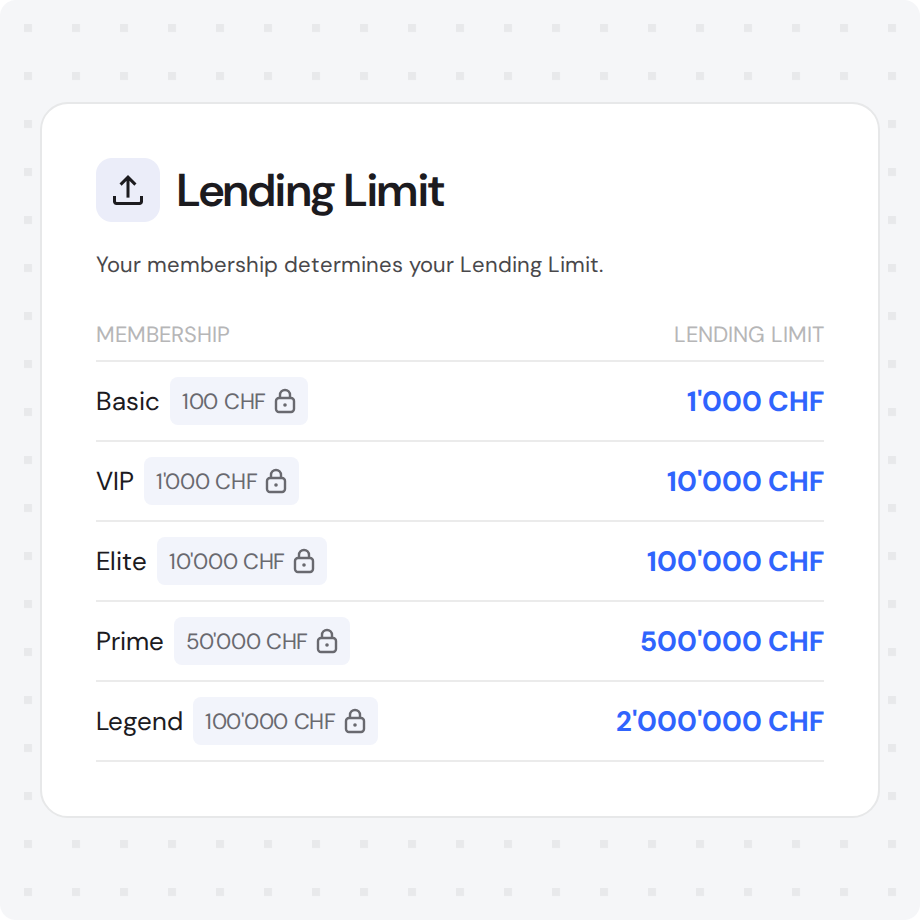
Your membership determines your lending limit. Membership prices: Basic 100 CHF, VIP 1'000 CHF, Elite 10'000 CHF, Prime 50'000 CHF, Legend 100'000 CHF.
Members fund real businesses they believe in. Borrowers and lenders connect directly.
Skew connects you to vetted borrowers on a Swiss platform affiliated with SO-FIT, a self-regulatory organization recognized by FINMA. You know exactly where your money goes.
Review the terms before you lend and manage everything from the dashboard. Your money, your rules.

Your lending rate is agreed upfront so you always know what you’ll earn. No market volatility. No variable rates.
Most people finish in a few minutes. You’re always in control.
What is Member Lending?

Member Lending is the core feature of the Skew platform. As a Skew member, you have exclusive access to fund vetted projects and businesses you believe in. Review borrower profiles, understand how the funds will be used, and choose where to lend, with a fixed APR and term agreed before you commit.
Interest is paid into your balance automatically every 24 hours, with no fee. At maturity, your capital comes back to your balance automatically once the borrower repays.
This is not a savings account. It is a member-based direct lending arrangement between you and a borrower, facilitated by Skew. The terms are transparent, the rate is fixed, and the control stays with you.
How does lending work on Skew?
Skew lists Member Lending opportunities from vetted borrowers. Each opportunity includes a borrower profile, the funding goal, the APR, and the lending term so you can review the details before deciding to participate.
If you choose to lend, you select the amount of your participation, from the minimum shown on the opportunity. Your funds are then reserved during the subscription period while other members decide whether to participate.
The loan starts automatically when either the full funding goal is reached or the minimum funding requirement is met at the end of the subscription period. Once the loan starts, your lending term begins and interest starts accruing daily.
Is the APR quoted as annual or monthly?
The APR is an annual rate and stays fixed for the full lending term. At 12% APR, a lending balance of 10'000 CHF earns about 3.29 CHF per day.
Can I withdraw my funds before the lending period ends?
No. Once your funds are committed to a lending opportunity, they are locked for the full lending term and cannot be withdrawn early.
Before lending, make sure you are comfortable leaving your funds committed for the entire lending period.
Interest you have already earned is paid to your balance every 24 hours, with no fee. On loans with a term of 6 months or more, you can also make an Early Interest Claim: you claim all the remaining interest now, for an Early Interest Claim Fee that starts at 20% and decreases as the loan gets closer to maturity. The fee is shown before you confirm. Your capital is still repaid at maturity.
What happens if a borrower defaults?
Borrowers are reviewed before being listed on the platform, and lending limits may increase gradually based on repayment performance and lending history. Any collateral provided is disclosed to members before funds are committed.
If a borrower defaults, Skew will take all reasonable steps available to recover funds on behalf of members. This may include enforcing loan agreements, pursuing legal remedies, and liquidating any collateral provided by the borrower.
However, Member Lending involves risk. If recovery efforts are unsuccessful or only partially successful, members may experience a loss on the affected lending position. There is no guarantee fund or insurance program that covers borrower defaults.
Every borrower is reviewed by Skew before its loan is listed. Each loan page shows who the borrower is, the collateral and the terms, so you know exactly who you are lending to before you commit.
Is Skew regulated?
Skew Labs SA is affiliated with SO-FIT as a financial intermediary (member no. 1504) under article 2 para. 3 of the Swiss Anti-Money Laundering Act (AMLA). SO-FIT is a self-regulatory organization recognized by the Swiss Financial Market Supervisory Authority (FINMA). Regulation does not eliminate lending risk, but it means the platform operates within a defined legal framework with obligations to its members.
Follow and subscribe to our channels.


Proudly Swiss. From Lugano, Switzerland.
© 2026 Skew. All rights reserved.
Skew is operated by Skew Labs SA, a Swiss company whose registered office is Via Ferruccio Pelli 13 c/o SiPaFid SA, 6900, Lugano, Switzerland. Skew Labs SA is affiliated with SO-FIT as a financial intermediary (member no. 1504) under article 2 para. 3 of the Swiss Anti-Money Laundering Act (AMLA). SO-FIT is a self-regulatory organization recognized by the Swiss Financial Market Supervisory Authority (FINMA). Skew’s services are actively offered only in Switzerland; their availability depends on your location, which may affect your rights and protections. Please read the Terms of Service and Privacy Policy that apply to you carefully. Taxes may be payable on profits. If you are outside Switzerland, you access Skew services on your own initiative and without solicitation.


